This site explains insurance claims for roof damage for homeowners in Oro Valley and the Tucson area: what homeowners policies usually cover, how the claim process works, how to document damage, and what to do if a claim is denied or underpaid. The articles below go into specific situations. This page is the overview. It’s general information, not legal advice, and your own policy wording always controls.
What policies usually cover, and what they don’t
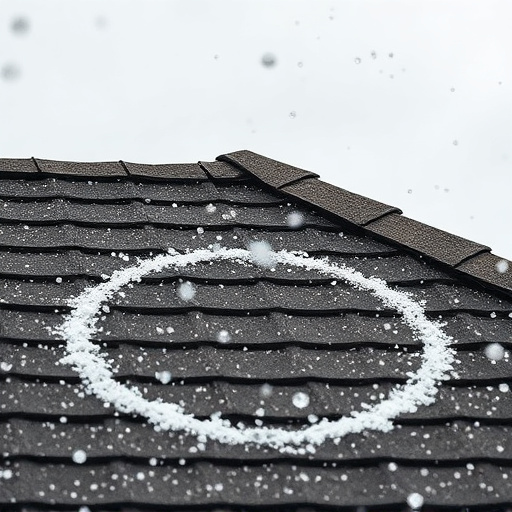
Most homeowners policies cover sudden, accidental damage, such as wind tearing off tiles or shingles, hail cracking tiles or puncturing a coating, or a tree limb falling on the roof. They generally don’t cover wear and tear: underlayment that dried out over twenty years, a foam roof that was never recoated, or a slow leak from flashing that failed with age.
That distinction drives most disputes. A monsoon storm often reveals a leak that age created, and the insurer may conclude the storm wasn’t the cause. Clear evidence of what the storm did, ideally compared with the roof’s condition before, is what makes the difference. See understanding roof damage coverage and denied claims in Arizona and does homeowners insurance cover roof replacement in Arizona?
Terms worth understanding before you file
- Deductible: the amount you pay before coverage starts. Check whether your policy has a separate deductible for wind or hail.
- Actual cash value (ACV): pays the depreciated value of the damaged roof, so an older roof gets less.
- Replacement cost value (RCV): pays what it costs to repair or replace with similar materials. Many RCV policies pay the ACV first and release the rest (the “recoverable depreciation”) after the work is done.
- Roof age limits or schedules: some policies reduce coverage for roofs over a certain age. Look for this on your declarations page.
- Mitigation: your duty to take reasonable steps, like tarping, to prevent further damage.
The claim process, step by step
- Protect the home. Tarp or seal damage to prevent more water getting in, and keep the receipts.
- Document everything. Dated photos and video of the roof (from the ground if it isn’t safe to climb), ceilings, walls and belongings. Note the date and time of the storm.
- Get a roof inspection. A licensed roofer’s report with photos and measurements helps show the extent of storm damage.
- Report the claim promptly. Policies require timely notice. Ask for a claim number and the adjuster’s contact information.
- Meet the adjuster. It helps to have your roofer present to point out damage the adjuster might miss, such as cracked tiles that look fine from below.
- Review the estimate. Compare the insurer’s scope with your roofer’s. Missing items, like underlayment, flashing or code-required upgrades, can be raised as a supplement.
- Complete the work and close out. Submit final invoices to recover any held-back depreciation.
See claim timelines, exclusions and resolution.
Partial damage and matching
Storms often damage one or two slopes, not the whole roof. Insurers may pay to repair only the damaged area, which can create a mismatch when the original tile or shingle is discontinued or has faded. How matching is handled depends on the policy and the insurer. Ask your roofer to document whether matching material is available. See claiming insurance for a partial roof replacement.
If your claim is denied or underpaid
- Ask for the reason in writing, with the policy language the insurer relied on.
- Get a second opinion from a licensed roofer, with photos showing storm-related damage.
- Request a re-inspection and submit your additional evidence.
- Check your policy’s appraisal clause, which can resolve disputes over the amount of a loss.
- Contact the state regulator. The Arizona Department of Insurance and Financial Institutions handles consumer complaints about insurers.
Red flags from contractors
After major storms, some contractors make promises that can get homeowners in trouble:
- Offering to “cover” or waive your deductible. This is a serious red flag and may amount to insurance fraud.
- Asking you to sign an assignment of benefits or a contract before you understand it.
- Promising a full replacement regardless of what the damage shows.
- Pressing you to sign before the adjuster has inspected.
Check any contractor’s license with the Arizona Registrar of Contractors before signing anything.
Prepare before the next storm
The best time to strengthen a future claim is before the storm. Keep a roof file with the installation date, warranty, inspection reports and dated photos of the roof in good condition. Read your policy for roof age limits and wind or hail deductibles. Get an inspection in spring so you have a baseline. For inspections, see the Oro Valley roof inspection guide; for urgent damage, the emergency roof repair guide.
For the basics in one place, see the complete guide to roof damage insurance claims in Oro Valley. The newest articles on this site are listed below.
Category: Insurance Claims for Roof Damage Oro Valley
Understanding Arizona Roof Damage Coverage & Denied Claims
Read more →
Homeowners Guide: Claim Timeline, Exclusions, & Resolution
Read more →Insurance Claims for Roof Damage Oro Valley — Complete Guide
Read more →
Does Homeowners Insurance Cover Roof Replacement in Arizona? A Tucson Homeowner’s Guide
Read more →
Navigating Roof Leak Repairs: Oro Valley Insurance Claims Guide
Homeowners in Oro Valley, Arizona, must understand insurance claims for roof damage, covering sudden.......
Read more →

Claim Assistance for Severe Roof Damage in Oro Valley
Oro Valley residents facing roof damage from storms or disasters can successfully navigate Insurance.......
Read more →

Roof Inspection & Repair After Insurance Claims in Oro Valley
In Oro Valley, insurance claims for roof damage involve a systematic process: homeowners report issu.......
Read more →

Claiming Insurance for Oro Valley Roof Damage: Your Guide
Oro Valley residents face frequent roof damage due to unique climate and geography. This guide clari.......
Read more →

Claiming Insurance for Partial Roof Replacement in Oro Valley
Oro Valley residents facing roof damage from weather events require a systematic approach for Insura.......
Read more →